Medicare’s annual election period runs from October 15 to December 7, and whatever you choose takes effect on January 1, 2027. It is the one window in the year when anyone on Medicare can switch a Medicare Advantage plan, move between Advantage and Original Medicare, or change a Part D drug plan. Plans re-price and re-tier their formularies every year, so the plan that was right in 2026 is not automatically right in 2027.
What the window is for
Three things. Check that your drugs are still on your plan’s formulary at the same tier, because that is where most of the surprise cost lives. Check that your doctors and hospital are still in network if you are on an Advantage plan. And compare the premium against the total cost, which for a drug plan means the deductible and the copays for what you actually take, not the monthly figure alone.
If your health coverage in retirement comes from a former employer, the annual window that matters is the employer’s, not this one. Enrolling in a standalone Medicare plan on your own can end retiree coverage that you cannot get back. Read the plan’s rules before you touch anything.
What the window is not for
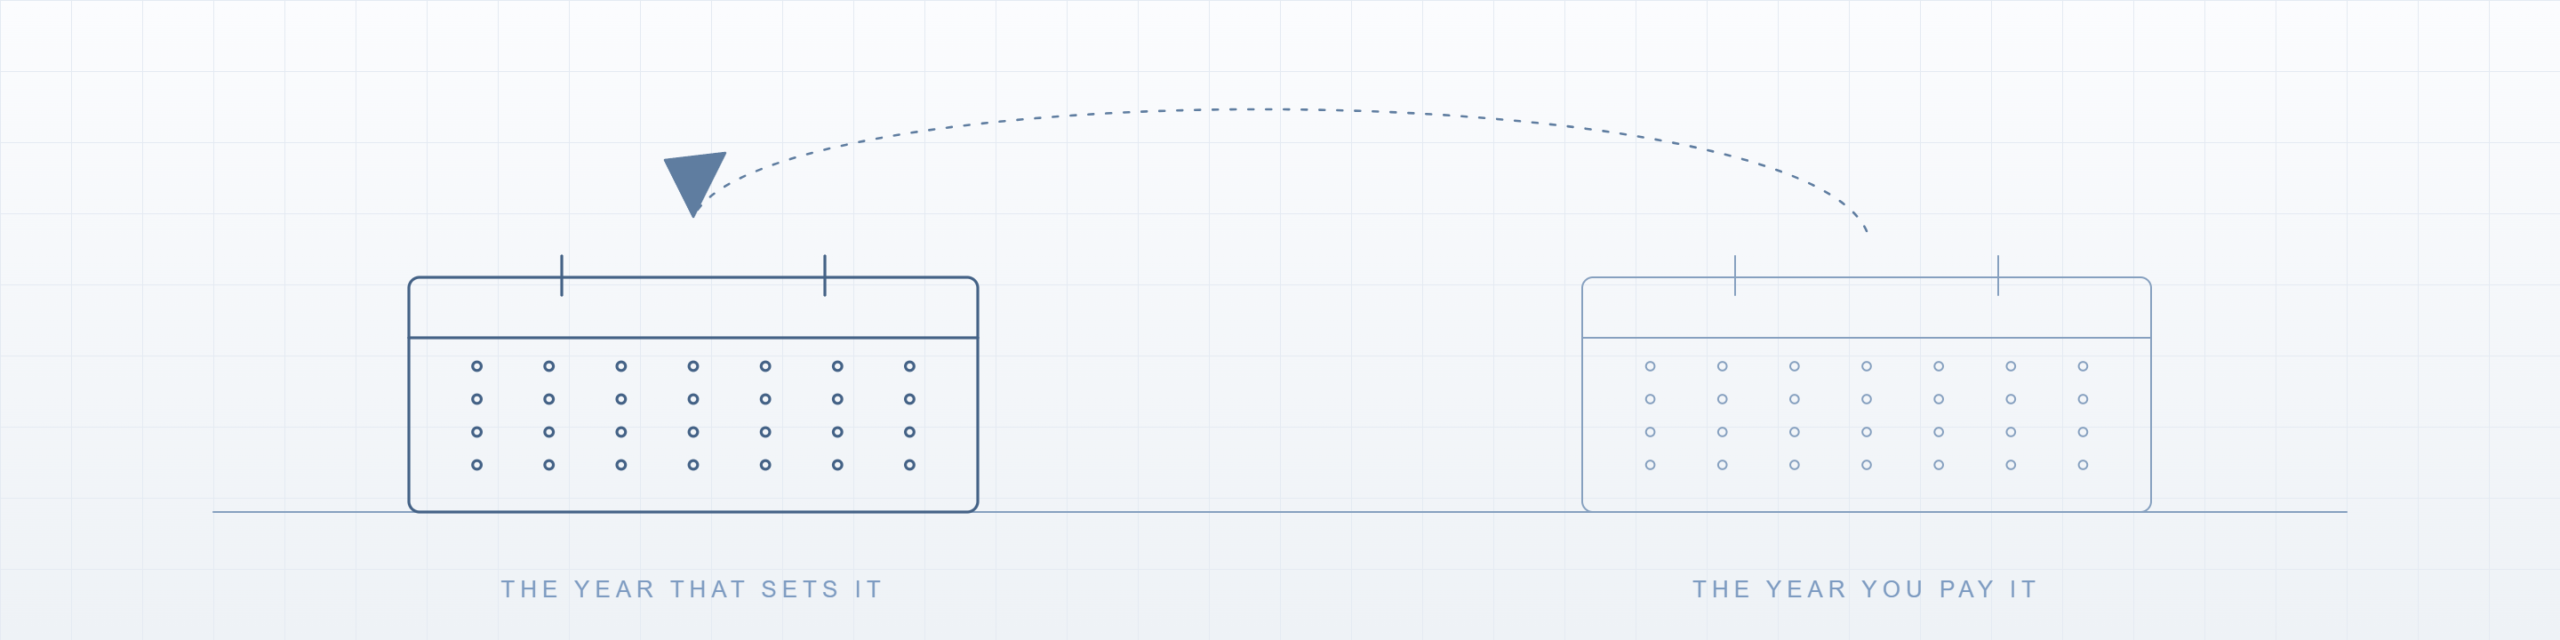
It does not change your income-related premium. The standard Part B premium is $202.90 a month in 2026, and the surcharge above that is set from the federal return you filed two years earlier. Your 2026 premium came from your 2024 return; your 2027 premium will come from your 2025 return, which is already filed. The income figure is your adjusted gross income plus tax-exempt interest, and the first threshold in 2026 is $109,000 for a single filer and $218,000 for a couple. One dollar over a threshold buys the whole next tier.
The 2027 brackets and premiums have not been published. The 2026 figures came out on November 14, 2025, and the 2027 figures should arrive at a similar point this fall, after the enrollment window has opened. The lower thresholds are indexed; the top ones, $500,000 and $750,000, are frozen until 2028, so the fifth bracket narrows a little every year.
If your income has dropped
Social Security will recompute the surcharge on a more recent year if you have had a life-changing event: retirement or reduced hours, marriage, divorce, the death of a spouse, the loss of a pension, or the loss of income-producing property. The form is SSA-44. The list is exclusive. A large capital gain, a Roth conversion, or simply a higher cost of living do not qualify, and the year the gain or the conversion landed in is the year you will pay for, two years on.
The North Jersey angle
A first-year retiree from PERS or TPAF is the classic case: the last full salary year sets the premium for the first retirement year, and the drop in income is exactly the kind of event SSA-44 exists for. File it the year you retire, with the retirement letter attached, rather than paying the surcharge and hoping it corrects itself.
Before December 7
Run your 2026 income through the Medicare calculator on the Calculators page to see how close you sit to a threshold, and remember that the income you are shaping now is the premium you will pay in 2028. The Medicare and IRMAA page covers the brackets in full. If you would like help reading a plan against your own prescriptions, start here.
Reviewed September 12, 2026. Sources: 42 CFR 422.62 (annual coordinated election period); CMS fact sheet, 2026 Medicare Parts A and B premiums and deductibles, November 14, 2025; Social Security, Medicare premiums: rules for higher-income beneficiaries, and Form SSA-44.
This article is general educational information and is not insurance or tax advice. Premiums, thresholds and enrollment rules are set by federal law and change every year. Confirm current figures with Medicare, Social Security and your plan before acting.
This page is general. Your situation is not.
The income that sets your premium was reported two years ago, and the surcharge moves in steps rather than smoothly. We can cover it in a short conversation, at no charge and with no obligation.
Book your Medicare ReviewNot ready to book? Answer a few questions about your situation, or send a message.
Booking is handled through Rosefinch Investment Advisors. North Jersey Retirement is not affiliated with, endorsed by, or sponsored by any government agency, retirement system, plan sponsor, or employer named on this site.