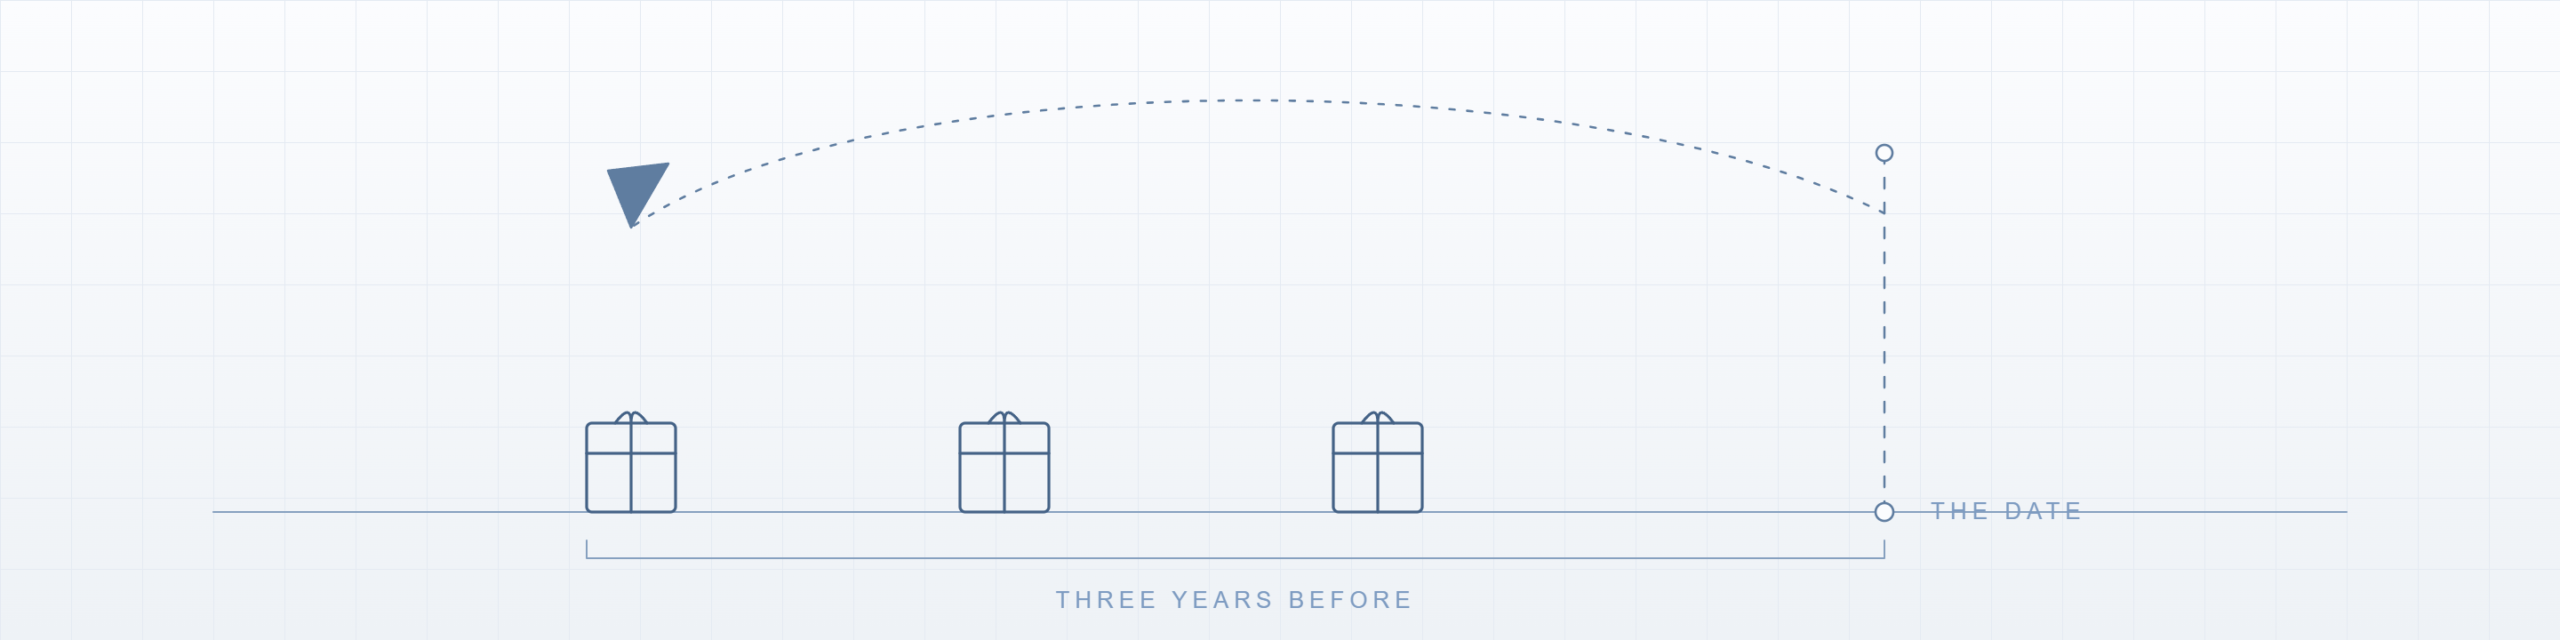
New Jersey has no gift tax and no estate tax. It repealed the estate tax for anyone dying on or after January 1, 2018. What it kept is the inheritance tax, and the inheritance tax has a rule about gifts that works differently from anything in the states around it. New Jersey presumes that a gift made within three years of death was made in contemplation of death, and taxes it as though it had passed at death.
The presumption, and what rebutting it involves
The New Jersey resident return asks the question directly: did the decedent, within three years of the date of death, transfer property valued at $500 or more without receiving full consideration for it. Anything that answers yes is reported, and the presumption attaches.
The presumption is rebuttable, and the part that matters is how. The instructions are specific: a claim that a transfer was not made in contemplation of death is supported by a supplemental affidavit setting out a detailed statement of the facts the claim rests on. That is a document somebody has to write, with facts in it, years after the event and after the person who could explain the gift has died. It is not an assertion on a form.
There is a carve-out for ordinary life. The instructions say incidental and non-material transfers, such as birthday gifts, holiday presents, and gifts marking weddings, graduations and births, are generally not treated as transfers in contemplation of death. Nobody is going to tax a wedding check. A transfer of real property is a different conversation.
New Jersey asks what you were thinking. New York does not
This is worth drawing out, because households that straddle the river get it backwards in both directions.
New York’s three-year rule is mechanical. It adds taxable gifts made in the last three years back into the estate, with a short list of exceptions, and intent plays no part in it. A gift made in perfect health for reasons unconnected to mortality is added back all the same, and there is nothing to rebut.
New Jersey’s rule is a presumption about a state of mind. It can be displaced by evidence, which makes it softer in principle and more work in practice. The burden sits with the estate, and the estate is arguing about what somebody was thinking.
There is also a difference in who pays. New York’s add-back enlarges the estate. New Jersey’s presumption taxes the person who received the gift, at the rate for their class, which means the same gift costs nothing to a child and 15% to a nephew.
What it costs, by who received it
Take a niece who inherits $300,000 and who was also given $100,000 during the three years before the death. Class D beneficiaries pay 15% on the first $700,000 and 16% above it. The inheritance alone produces $45,000 of tax. With the gift pulled back, the figure taxed is $400,000 and the tax is $60,000. The gift added $15,000, exactly 15% of what was given away, and giving it during life achieved nothing for tax.
The same gift to a brother, who is Class C, adds $11,000 rather than $15,000, because Class C pays 11% in that range. To a child, it adds nothing, because Class A is exempt. The gift did not change. The relationship did.
One consequence is worth stating plainly: for a family whose beneficiaries are all Class A, the three-year rule is an administrative question rather than a tax one. For a family leaving anything to siblings, nieces, nephews or friends, late gifting is not a strategy.
The rule with no time limit at all
The three years get the attention, and a different category catches more North Jersey families. A transfer intended to take effect at or after death is taxable whenever it was made. There is no three-year limit on it.
The common version is the parent who deeds the house to a child but keeps the right to live in it. That is a retained life estate, and the house stays inside the tax no matter how many years pass. Where the child is Class A no tax follows, but the property is still part of the return, and the lien and waiver machinery still applies to it.
Where to look
The New Jersey inheritance tax page sets out the beneficiary classes, the rates, the exemptions, and the lien that exists whether or not any tax is owed. The inheritance tax calculator now takes gifts received in the last three years as a separate figure and shows what the presumption adds for that beneficiary’s class. If you would like it worked out with you, start here.
Published September 13, 2026. Sources: New Jersey Division of Taxation, Form IT-R, Inheritance Tax Resident Return, and its instructions, on the three-year question, the $500 figure, the supplemental affidavit, the incidental gifts carve-out, transfers intended to take effect at or after death, and the Class C and Class D rate schedules; the Division’s Inheritance and Estate Tax pages on the repeal of the estate tax for deaths on or after January 1, 2018. The New York comparison is drawn from the Instructions for Form ET-706 and New York Tax Law section 954.
This article is general educational information and is not tax or legal advice. Inheritance tax questions turn on specific facts and on specific beneficiary relationships. Confirm current figures with the New Jersey Division of Taxation, and take estate planning decisions to an attorney who practices in this area.
This page is general. Your situation is not.
The presumption reaches gifts made in the three years before death, and rebutting it depends on evidence gathered while there is still time. We can cover it in a short conversation, at no charge and with no obligation.
Book your Inheritance Tax ReviewNot ready to book? Answer a few questions about your situation, or send a message.
Booking is handled through Rosefinch Investment Advisors. North Jersey Retirement is not affiliated with, endorsed by, or sponsored by any government agency, retirement system, plan sponsor, or employer named on this site.