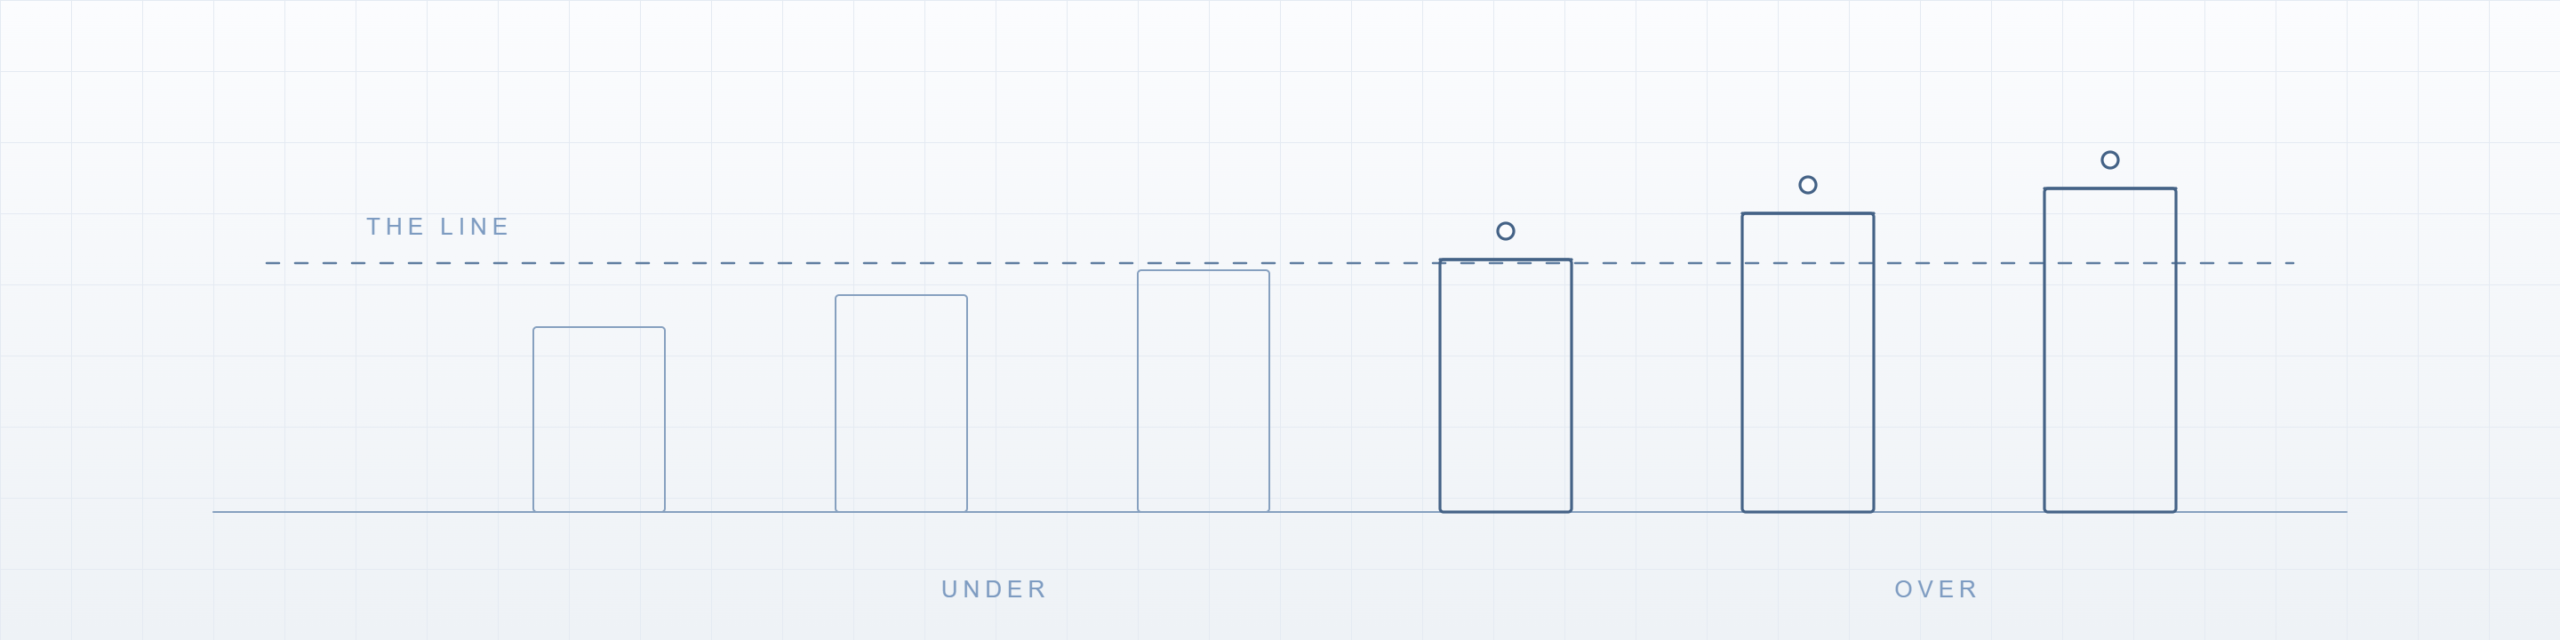
New Jersey’s pension exclusion is one of the most valuable retirement tax rules in the state and one of the least understood, because it does not phase out the way people expect. It steps down, and then it disappears. The step that matters most is at $150,000 of total income, and the withdrawal that pushes a household over it can be the one taken in December.
The rule
If you or your spouse are 62 or older, or disabled under Social Security’s definition, on December 31, you can exclude taxable pension, annuity and IRA income up to $100,000 on a joint return, $75,000 for a single filer, head of household or qualifying surviving spouse, and $50,000 if married filing separately. That full amount is available only when your total income for the year is $100,000 or less.
Between $100,000 and $125,000 of total income, the exclusion becomes a percentage of your pension income: 50% joint, 37.5% single, 25% separate. Between $125,000 and $150,000 it halves again: 25%, 18.75% and 12.5%. Above $150,000 there is no exclusion. The test is on the whole of your total income, so one dollar over $150,000 does not cost you one dollar of exclusion; it costs you all of it.
What counts toward the line
Total income for this test is line 27 of the NJ-1040, which is everything New Jersey taxes: wages, the taxable part of pension and IRA withdrawals, interest, dividends, capital gains, rental income and business income. Social Security is not New Jersey income and is not in the test. Your PERS or TPAF allowance is in it. A Roth conversion is in it, because New Jersey taxes the conversion in the year you make it, apart from the return of contributions you already paid state tax on.
So a couple with a $70,000 public pension, $40,000 of dividends and interest, and an IRA withdrawal of $35,000 sits at $145,000 and keeps 25% of the exclusion. Add a $10,000 withdrawal in December for a car, and they are at $155,000, the exclusion is gone, and the whole $105,000 of pension and IRA income is taxed. The December withdrawal did not cost tax on $10,000. It cost tax on the exclusion it destroyed.
The year-end move
Estimate your total income before you take anything else in November and December. If you are under $150,000 with room to spare, nothing changes. If you are close, the choices are to take the withdrawal in January instead, to take it from a Roth account that New Jersey does not tax, to defer a capital gain, or to accept the loss knowingly because the cash is needed. What you should not do is find out in April. A required minimum distribution still has to be taken by December 31, so if one is pending it should be in the estimate first.
The same logic runs the other way for Roth conversions. A conversion in a year you are already over $150,000 costs nothing extra in exclusion, because there is none left to lose; a conversion in a year you are at $120,000 can cost a band. Model the year, not the transaction.
The calculator
The pension exclusion checker on the Calculators page takes your filing status, total income and pension income and returns the exclusion you keep and the amount of room before the next step down. The New Jersey Retirement Taxes page covers the rest of the return. If you would like the year-end estimate run with you, start here.
Reviewed September 12, 2026. Sources: N.J.S.A. 54A:6-10; New Jersey Division of Taxation, GIT-1&2 Retirement Income (rev. January 2026); NJ-1040 instructions, lines 27 and 28.
This article is general educational information and is not tax advice. Exclusion amounts, income bands and line references are set by New Jersey law and can change. Confirm current figures with the New Jersey Division of Taxation and your tax preparer before acting.
This page is general. Your situation is not.
The exclusion is lost in full once total income crosses the line, and a December withdrawal is settled for that year. We can cover it in a short conversation, at no charge and with no obligation.
Book your Retirement ReviewNot ready to book? Answer a few questions about your situation, or send a message.
Booking is handled through Rosefinch Investment Advisors. North Jersey Retirement is not affiliated with, endorsed by, or sponsored by any government agency, retirement system, plan sponsor, or employer named on this site.